Restaurant Insurance in Minnesota
Restaurant Insurance in Minnesota, Built for What Actually Happens in a Minnesota Kitchen
Nelson Insurance Services is an independent local agency in Prior Lake, MN. We help restaurants, cafés, and catering owners in Scott County and across Minnesota protect their kitchen, dining room, staff, and bottom line—from a burst pipe in January to a busy Friday night rush.
Call 952-469-0412 for a Free Quote on Restaurant Insurance in Minnesota
Restaurant Insurance in Minnesota and What Minnesota Actually Requires from Restaurant Owners
Minnesota requires workers’ compensation insurance for every employer with at least one employee, full-time or part-time. Restaurants get no exception, and with kitchen staff, servers, and dishwashers on payroll, this applies to nearly every restaurant in the state. General liability coverage isn’t mandated by the same kind of statute, but it’s effectively required in practice — it’s how a restaurant covers the most common claim it will ever face, a customer injury or a food-related illness claim.
Before any of that, you’ll also need a food and beverage license from the Minnesota Department of Health (or your local delegated health department), which requires a passed inspection and, in most cases, a certified food manager on staff. If you serve alcohol, one more requirement applies: Minnesota Statute § 340A.409 requires proof of liquor liability insurance before issuing or renewing a liquor license. Standard restaurant policies exclude alcohol-related claims entirely, so any restaurant with a bar or wine list needs liquor liability coverage in addition to its core policy. See our liquor liability insurance page for specifics or get a restaurant insurance quote to talk through your full setup.
The Nelson Coverage Menu — From Prep to Fine Dining
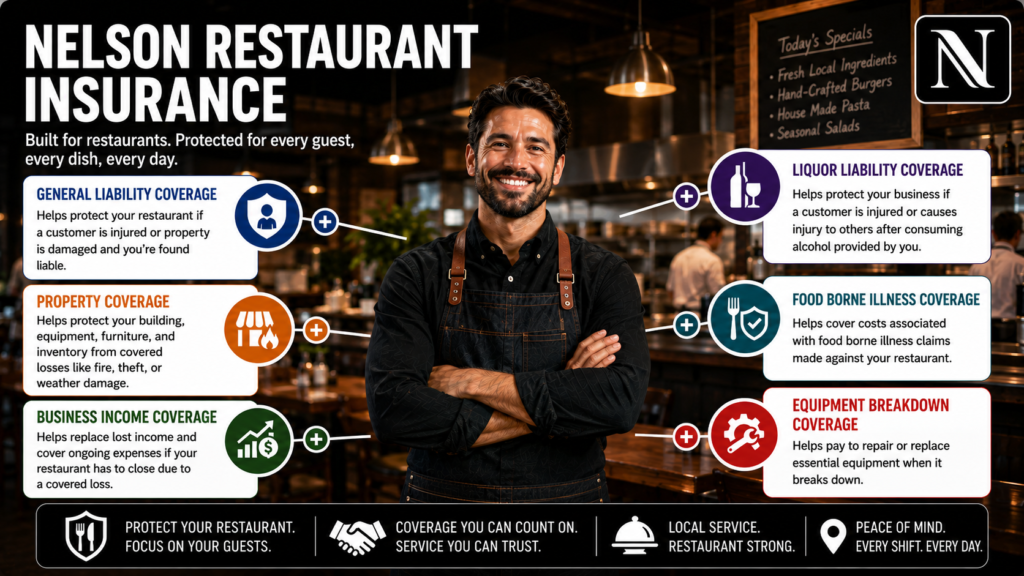
Restaurant coverage builds the same way a menu does — core dishes first, then the additions that make the whole thing complete. Here’s how the three common levels compare for Minnesota restaurants.
Prep — Minimum Coverage
General liability and workers’ compensation only. Meets the basic legal requirement, but leaves the building, equipment, inventory, and income exposed if a kitchen fire, storm, or extended closure ever hits.
Full Service — Standard Coverage
A Business Owner’s Policy (BOP) bundling general liability with commercial property, plus business income coverage and equipment breakdown protection. The most common setup for Prior Lake area restaurants, cafés, and catering businesses.
Fine Dining — Complete Protection
Everything in Full Service, plus liquor liability, food spoilage coverage, commercial auto for delivery vehicles, and cyber liability for POS systems and online ordering. Built for restaurants that want one less thing to worry about when the unexpected happens.
The Restaurant Coverage Types Minnesota Owners Ask About Most
Every policy combines these building blocks. We’ll help you choose the ones that make sense for your restaurant, menu, and budget.
General Liability
Covers customer injuries, property damage, and food-related illness claims arising from your restaurant’s operations—the foundation of nearly every restaurant policy.
Commercial Property
Covers your building, kitchen equipment, furniture, and inventory against fire, storm, theft, and other covered losses — especially relevant given Minnesota’s snow load and freeze risk.
Business Income (Business Interruption)
Replaces lost income and helps cover ongoing expenses if a covered loss forces your restaurant to close temporarily, whether that’s a kitchen fire or a burst pipe.
Equipment Breakdown
Covers the repair or replacement of walk-in coolers, ovens, and other essential equipment after a mechanical or electrical breakdown — losses a standard property policy often excludes.
Food Contamination & Spoilage
Covers inventory loss from a power outage, equipment failure, or contamination event, plus cleanup costs and lost income while you get back up and running.
Liquor Liability
Required separately if you serve alcohol, covering dram shop claims that general liability specifically excludes for any business that sells or serves liquor.
Commercial Auto
Covers delivery vehicles and catering transport, since a personal auto policy typically excludes business use.
Cyber Liability
Covers costs tied to a data breach, payment fraud, or system outage — increasingly relevant as more restaurants rely on POS systems, online ordering, and reservation platforms.
Restaurant Insurance in Minnesota - Why Minnesota Restaurant Owners Choose Us
We’re not tied to a single carrier for restaurant insurance in Minnesota. We compare rates and coverage across multiple Minnesota-licensed insurers to build a policy that fits your restaurant, not a generic template.
- We shop it for you — one conversation, multiple quotes, no repeating your information to five different call centers.
- We know Minnesota winters — pipe bursts, roof collapse from snow load, and power outages all factor into how we recommend coverage.
- We’re local—based in Prior Lake, serving Scott County restaurants, cafés, and caterers who face the same seasons and staffing challenges we do.
- We handle liquor liability too — so your bar or wine list is covered under the same relationship, not a separate scramble.
The Common Ways You Can Save on Restaurant Insurance in Minnesota
Ask about these when you call — most restaurants qualify for at least one or two.
- Business Owner’s Policy (BOP) bundling — combine general liability and property coverage for a lower overall rate.
- Fire suppression & safety systems — monitored systems and up-to-date kitchen suppression equipment can reduce your premium.
- Claims-free history — a clean claims record is rewarded across most carriers.
- Staff safety training — documented training programs can help lower workers’ comp costs over time.
Proudly Serving Restaurants Across Prior Lake, Scott County, and Minnesota
Prior Lake · Savage · Shakopee · Lakeville · Elko New Market · Credit River · Scott County, MN
Get a Real Quote on Restaurant Insurance in Minnesota from a Real Local Agent
No spam, no runaround — just a straightforward conversation about what coverage your restaurant actually needs.
Nelson Insurance Services · 952-469-0412 · Prior Lake, MN
Independent insurance agency serving Prior Lake, Savage, Shakopee, Lakeville, Scott County, and all of Minnesota. Personal and business insurance coverage from multiple carriers, chosen to fit you.
FAQ
Workers’ compensation insurance is required for any restaurant with at least one employee, with no exceptions based on part-time status or headcount. General liability isn’t mandated by the same kind of statute, but it’s effectively required in practice and often required by landlords. Restaurants serving alcohol also need a separate liquor liability policy, per Minn. Stat. § 340A.409, to legally hold a liquor license.
Yes, typically through your general liability policy, which covers claims of bodily injury or illness arising from your restaurant’s operations, including food-related illness claims. Documentation, food safety practices, and prompt reporting all matter if a claim like this comes up.
This is where food contamination and spoilage coverage, along with business income coverage, come in. Spoilage coverage helps replace lost inventory after a power outage or equipment failure, while business income coverage helps replace lost revenue and ongoing expenses if a covered event forces you to close for repairs.
Yes, if you serve alcohol. Standard general liability and Business Owner’s Policies specifically exclude liquor liability claims for any business licensed to sell or serve alcohol. You need a separate liquor liability policy to meet Minnesota’s liquor license requirement and cover a dram shop claim.
GET A QUICK QUOTE
it only takes a minute
Ready to Protect What Matters Most?
Let's find the right coverage for you or your business.