Commercial Auto Insurance in Minnesota
Commercial Auto Insurance for Minnesota Businesses That Live on the Road
Nelson Insurance Services is an independent local agency in Prior Lake, MN. We help contractors, service businesses, and fleet owners across Scott County & beyond get commercial auto coverage that protects the vehicle, the driver, and the business behind the wheel—and meets the limits required by any contract or bid.
Call 952-469-0412 for a Free Commercial Auto Quote in Minnesota
What Minnesota Actually Requires for Business Vehicles
If a vehicle is titled in your business name or used primarily for work, the state requires commercial auto insurance in Minnesota. A personal auto policy typically excludes business use entirely, and the insurer can deny a claim outright if it learns the vehicle was working at the time. The state’s minimum requirements mirror personal auto under Minn. Stat. § 65B.49: 30/60/10 liability, $40,000 in Personal Injury Protection, and 25/50 uninsured/underinsured motorist coverage. The Minnesota Department of Commerce publishes the same baseline for both personal and business vehicles.
In practice, that legal floor rarely satisfies the businesses you work with. Most general contractors, cities, and commercial clients want a Certificate of Insurance showing $1,000,000 in combined single limit (CSL) liability before they sign a contract or let you on a job site, regardless of what Minnesota’s statutory minimum technically allows. If your vehicles cross into trucking or interstate hauling territory, FMCSA rules can add additional federal minimums. Get a quote for commercial auto insurance in Minnesota or see how this fits with a broader business insurance package.
The Nelson Coverage Route — From Local Route to Full Fleet
Commercial auto insurance in Minnesota typically scales with how many vehicles you run and what your contracts demand. Here’s how the three common levels compare for Minnesota businesses.
Local Route — State Minimum
30/60/10 liability, PIP, and required UM/UIM on a single work vehicle. Legal to drive, but well below the $1,000,000 CSL that most contracts and Certificates of Insurance now expect.
Standard Route — $1 Million CSL
The most common setup for Prior Lake area contractors and service businesses: $1,000,000 combined single limit liability, plus physical damage coverage for the vehicle itself. This is the limit most GCs, property managers, and municipal bids specifically ask for.
Full Fleet — Complete Protection
Multiple vehicles under one policy, Hired & Non-Owned Auto (HNOA) coverage for employees and rental vehicles used for work, and a commercial umbrella layered on top. Built for businesses that don’t want a single accident to threaten the whole operation.
The Types of Commercial Auto Insurance in Minnesota Businesses Ask About Most
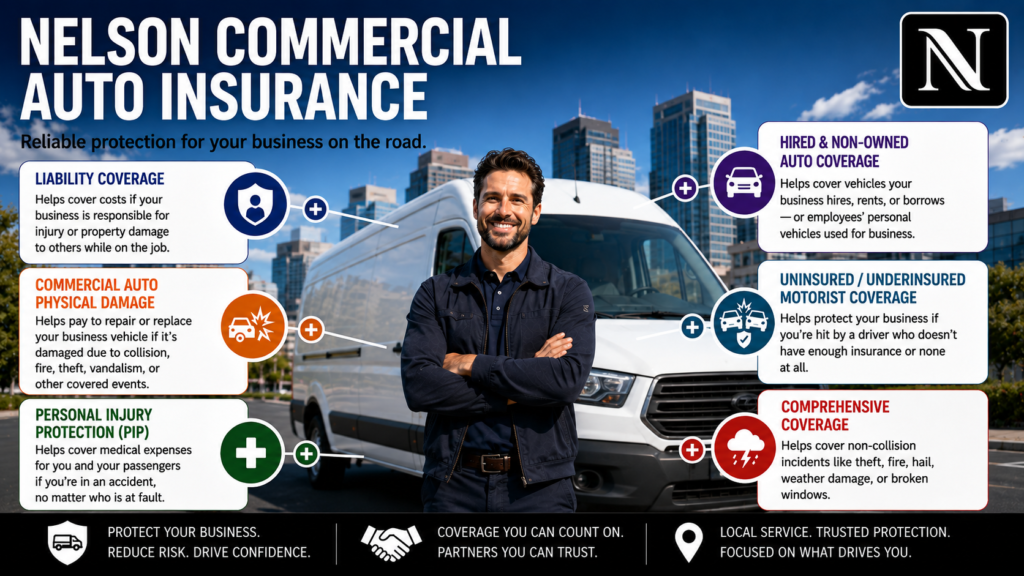
Commercial auto insurance in Minnesota brings these building blocks together. We’ll help you choose the ones that fit your vehicles, your work, and your budget.
Liability Coverage
Pays for injuries or property damage you cause to others while operating a business vehicle. Minnesota requires 30/60/10 at minimum, though $1,000,000 CSL is the common contract standard.
Physical Damage Coverage
Collision and comprehensive coverage that repairs or replaces your work vehicle after an accident, theft, or weather event — critical for vehicles your business can’t operate without.
Hired & Non-Owned Auto (HNOA) Coverage
Covers liability when an employee uses their own vehicle for work, or your business rents a vehicle. A gap standard commercial auto policies don’t automatically fill.
Uninsured / Underinsured Motorist Coverage
Required in Minnesota, and especially important for businesses whose vehicles are on the road daily and represent a larger share of the company’s assets.
Medical Payments Coverage
Covers medical expenses for you, an employee, or a passenger after a work-vehicle accident, regardless of fault.
Why Businesses Choose Us for Commercial Auto Insurance in Minnesota?
We’re not tied to a single carrier. We compare commercial auto insurance in Minnesota, rates and coverage across multiple Minnesota-licensed insurers, to build a policy that fits your vehicles and your contracts.
- We shop it for you — one conversation, multiple quotes, no repeating your information to five different call centers.
- We know what COIs actually require — and make sure your limits match what your contracts and bids ask for.
- We’re local — based in Prior Lake, serving Scott County businesses that deal with the same winter roads and seasonal work we do.
- We catch the HNOA gap — a common blind spot for businesses whose employees use personal vehicles for work.
Common Ways Businesses Save on Commercial Auto Insurance in Minnesota
Ask about these when you call — most businesses qualify for at least one or two.
- Multi-policy bundling — combine commercial auto with general liability or a Business Owner’s Policy.
- Multi-vehicle discounts — insure your full fleet under one policy for a lower per-vehicle rate.
- Safe driver/telematics programs — discounts for monitored driving behavior and clean records.
- Claims-free history — a clean claims record is rewarded across most carriers.
Proudly Serving Businesses Across Prior Lake, Scott County and Minnesota
Prior Lake · Savage · Shakopee · Lakeville · Elko New Market · Credit River · Scott County, MN
Get a Real Quote on Commercial Auto Insurance in Minnesota from a Real Local Agent
Get commercial auto insurance in Minnesota with no spam, no runaround—just a straightforward conversation about what coverage your vehicles need and what your contracts require.
Nelson Insurance Services · 952-469-0412 · Prior Lake, MN
Independent insurance agency serving Prior Lake, Savage, Shakopee, Lakeville, and Scott County. Get commercial auto insurance in Minnesota from multiple carriers, chosen to fit you.
FAQ
Yes, if a vehicle is titled to your business or used primarily for work. Minnesota requires the same minimum coverage as personal auto — 30/60/10 liability, $40,000 PIP, and 25/50 uninsured/underinsured motorist coverage, per Minn. Stat. § 65B.49 — but applied through a commercial policy rather than a personal one.
Usually not safely. Personal auto policies typically exclude business use, which means a claim involving a work-related accident could be denied entirely, even if you’ve paid your personal premium faithfully. A commercial auto policy is built specifically to cover business use.
HNOA coverage protects your business when an employee uses their own vehicle for work, or when your business rents a vehicle. If your team ever drives personal cars for deliveries, job sites, or client visits, this is a common and often overlooked gap in standard commercial auto coverage.
Most general contractors, property managers, and municipal bids require a Certificate of Insurance showing $1,000,000 in combined single limit liability, well above Minnesota’s 30/60/10 statutory minimum. We’ll help ensure your policy matches what your specific contracts and clients require.
GET A QUICK QUOTE
it only takes a minute
Ready to Protect What Matters Most?
Let's find the right coverage for you or your business.