Auto Insurance in Minnesota
Auto Insurance in Minnesota - Built for MN Roads, Not Fine Print
Buy your auto insurance in Minnesota from Nelson Insurance Services, an independent local agency in Prior Lake, MN. We compare real Minnesota carriers side by side, explain state requirements, and help you carry the right amount of coverage—not just the legal minimum.
Call 952-469-0412 for a Free Quote on Auto Insurance in Minnesota
What Minnesota Actually Requires from Drivers
Minnesota is a no-fault insurance state, meaning your policy pays your medical bills after an accident, regardless of who caused it. Under Minnesota’s No-Fault Automobile Insurance Act (Minn. Stat. ch. 65B), every driver must carry:
- Liability coverage of 30/60/10 — $30,000 per person and $60,000 per accident for bodily injury, plus $10,000 for property damage
- $40,000 in Personal Injury Protection (PIP) — split into $20,000 for medical expenses and $20,000 for wage loss and replacement services
- 25/50 uninsured motorist (UM) coverage
- 25/50 underinsured motorist (UIM) coverage
A quick correction worth making clear: UM and UIM coverage are both required by Minnesota law, not optional — a detail some drivers (and even some agents) get wrong. You can read the state’s own breakdown in the Minnesota Department of Commerce Auto Insurance Guide. Even with UIM required, the minimum limit is often thin — many drivers carry only the state floor, so a serious accident can still outrun your coverage fast. That’s exactly where a local, independent agent earns their keep — helping you understand not just what’s legal, but what’s enough. See our home insurance page if you’re bundling coverage, or head straight to get a quote.
The Nelson Coverage Depth Gauge — How Deep Is Your Protection?
Minnesota’s name comes from the Dakota Indian language. The words mnisota or Mni Sota Makoce. Translated, it means sky-linted water, or land where the waters reflect the clouds. Let’s compare rates for Minnesota drivers.
Surface — State Minimum
30/60/10 liability, PIP, and the required 25/50 UM/UIM. Legal to drive, but a single serious accident can quickly exceed these limits —leaving your savings, wages, and even your home exposed to a lawsuit for the difference. These low limits are NOT recommended.
Mid-Depth — Standard
Higher liability limits plus increased UM/UIM coverage. This is the most common recommendation for Minnesota households, since it protects you against the many drivers who carry only the state minimum.
Full Depth — Complete Protection
100/300/100 liability, higher UM/UIM, comprehensive & collision. Built for newer vehicles, teen drivers, or anyone who wants one less financial risk to think about. This is where most of our Minnesota clients land once they see the numbers.
The Questions Most Drivers Ask About Auto Insurance in Minnesota
Auto insurance in Minnesota brings these building blocks together. We’ll help you choose the ones that fit your vehicle, driving history, and budget.
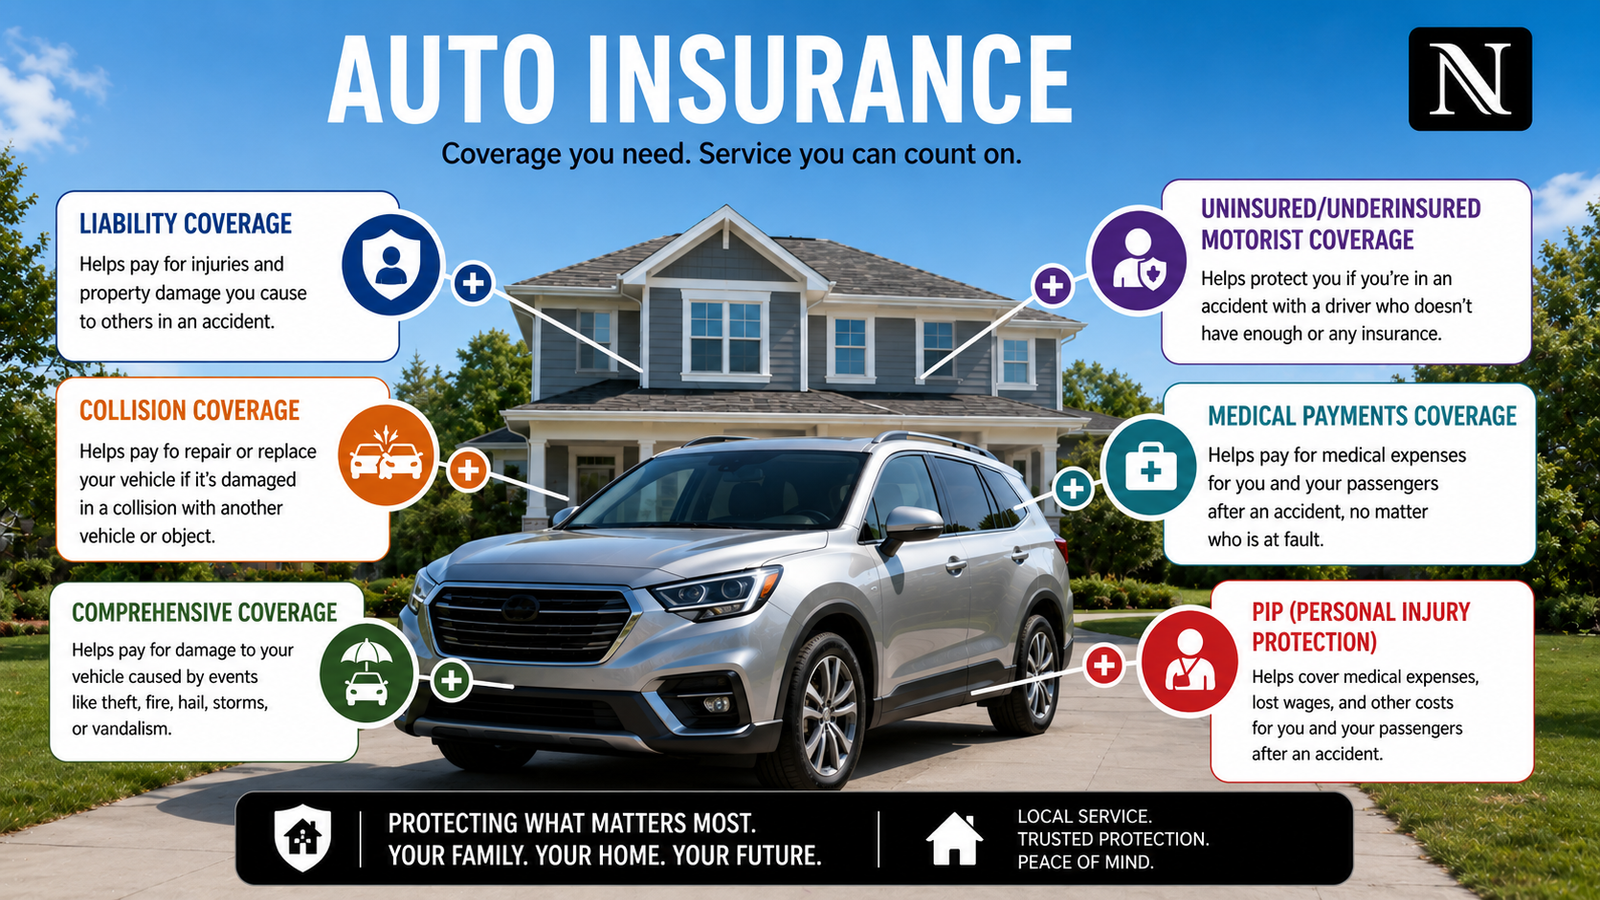
Liability Coverage pays for injuries or property damage you cause to others. Minnesota requires 30/60/10 at minimum, but higher limits are widely recommended.
Personal Injury Protection (PIP) is Minnesota’s no-fault coverage. It pays your medical expenses and lost wages after an accident, no matter who was at fault. Details are in the Minnesota Commerce Department’s auto insurance guide.
Uninsured / Underinsured Motorist (UM/UIM): Protects you when the other driver has no insurance, or not enough. Both are required in Minnesota at 25/50 minimums — we help you decide whether to go beyond that floor.
Collision Coverage: Repairs or replaces your vehicle after a crash, regardless of fault. Often required if you’re financing or leasing.
Comprehensive Coverage: Covers non-collision events — hail, deer strikes, theft, and windshield damage are especially relevant here in Minnesota, which regularly ranks among the top states for hail and deer-related claims.
SR-22 filings are required after certain violations to prove financial responsibility to the state under Minn. Stat. 169.797. We can file it and find a carrier who will write the policy. Learn more on our SR-22 filing page.
Why Minnesota's Drivers Choose Us - Auto Insurance in Minnesota
Nelson Insurance Services isn’t tied to a single carrier. We compare rates and coverage across multiple Minnesota-licensed insurers to find the best fit for your situation.
- We will shop for you — one conversation, multiple quotes. No need to repeat your information to five different call centers.
- We know Minnesota’s rules — no-fault laws, PIP thresholds, and UM/UIM requirements are second nature to us, not something you have to research on your own.
- We’re local — based in Prior Lake, serving Scott County. When you call, you’re talking to someone who knows the roads and the weather you’re insuring against.
- We stick around after the sale — life changes, new cars, new drivers, a move across town. We adjust your policy as your life changes, not just at renewal. See how we handle policy updates on our About page.
Common Ways Minnesota Drivers Save on Auto Insurance in Minnesota
When you call about auto insurance in Minnesota, ask about these —not every driver qualifies for every discount, but most households qualify for at least two or three.
Proudly Serving Prior Lake, the Surrounding Scott County Area, and All of Minnesota
Prior Lake · Savage · Shakopee · Lakeville · Elko New Market · Credit River · Scott County, MN
Get a Real Auto Insurance in Minnesota, From a Real Local Independent Agent
No spam, no runaround — auto insurance in Minnesota — just a straightforward conversation about what coverage makes sense for you, your vehicle, and your budget. Buy your auto Insurance in Minnesota from us.
Nelson Insurance Services · 952-469-0412 · Secure Auto Insurance in Minnesota from our Independent insurance agency serving Prior Lake, Savage, Shakopee, Lakeville, Scott County, and all of Minnesota. Auto, home, and business insurance coverage from multiple carriers, chosen to fit you. Contact us · About our agency
FAQ
Minnesota requires liability coverage of 30/60/10 ($30,000 per person and $60,000 per accident for bodily injury, $10,000 for property damage), plus $40,000 in Personal Injury Protection and 25/50 uninsured/underinsured motorist coverage. Minnesota is a no-fault state, so PIP applies regardless of who caused the accident. Full details are available in the Minnesota Department of Commerce’s guide and Minn. Stat. 65B.49.
For most drivers, no. States set minimums years ago and haven’t kept pace with vehicle values or medical costs. Many agents recommend liability limits closer to 100/300/100 along with higher UM/UIM limits, since a single serious accident can quickly exceed the state floor.
The cost Auto Insurance in Minnesota depends on your driving history, vehicle, coverage limits, household drivers and consumer reports. There’s not a single statewide number that applies to everyone. The most reliable way to know your real cost is a personalized quote, since bundling, discounts, and carrier selection can significantly affect your premium.
An SR-22 may be required after certain violations, like a DUI or driving without insurance, under Minn. Stat. 169.797, to prove financial responsibility to the state. We can help file an SR-22 and find a carrier willing to write a policy during that period. More on our SR-22 page.
GET A QUICK QUOTE
it only takes a minute
Ready to Protect What Matters Most?
Lees find the right coverage for you or your business.