Homeowners Insurance in Minnesota
Homeowners Insurance in Minnesota That Actually Holds Up in Our Weather
Nelson Insurance Services is an independent local agency in Prior Lake, MN. We compare real Minnesota carriers side by side, explain what’s driving rate increases statewide, and help you build a policy that holds up when hail, wind, or a frozen pipe puts it to the test.
Call 952-469-0412 for a Free Quote on Homeowners Insurance in Minnesota
Is Homeowners Insurance in Minnesota Required?
No — law doesn’t require homeowners insurance in Minnesota. But if you have a mortgage, your lender will require it as a condition of the loan, and it’ll stay required for as long as you’re paying it off.
Even homeowners who own their home outright still face the full cost of a fire, storm, or liability claim out of pocket without coverage.
Homeowners insurance in Minnesota has been rising sharply. According to Insurify’s 2026 report, the state’s average annual premium rose about 34% in 2025 — the largest increase of any state — landing near $3,530 by year-end, with a further 4% rise projected for 2026.
Other sources using different coverage assumptions put a “typical” Minnesota policy now closer to the $2,200–$2,700 range, so your number will depend heavily on your dwelling coverage, deductible, and ZIP code. Severe hail and wind exposure, rising rebuilding costs, and higher reinsurance costs are the biggest drivers across almost every estimate.
Shopping across multiple carriers, rather than accepting a single renewal quote, is one of the most effective ways to manage that increase. Request a quote on your homeowners insurance in Minnesota, and we’ll do that shopping for you.
The Nelson Coverage Build — From Foundation to Full Protection
Homeowners insurance in Minnesota is built in layers, like a house. Here’s how the three common levels compare for Minnesota homeowners.
Foundation — Lender-Minimum Coverage
Dwelling coverage meets the mortgage requirement and includes basic liability. It checks the lender’s box but often underestimates true rebuilding cost and leaves gaps in personal property and liability protection.
Framed — Standard Coverage
Dwelling coverage matched to real rebuilding cost, plus personal property, liability, and loss-of-use coverage. This is the most common setup for Prior Lake homeowners, and the baseline we build every quote from.
Full Build — Complete Protection
Replacement cost coverage, higher liability limits, sewer/water backup coverage, and scheduled coverage for valuables like jewelry or equipment. Built for homeowners who want one less financial risk to think about after a bad storm.
The Types of Homeowners Insurance in Minnesota That Home Owners Ask About Most
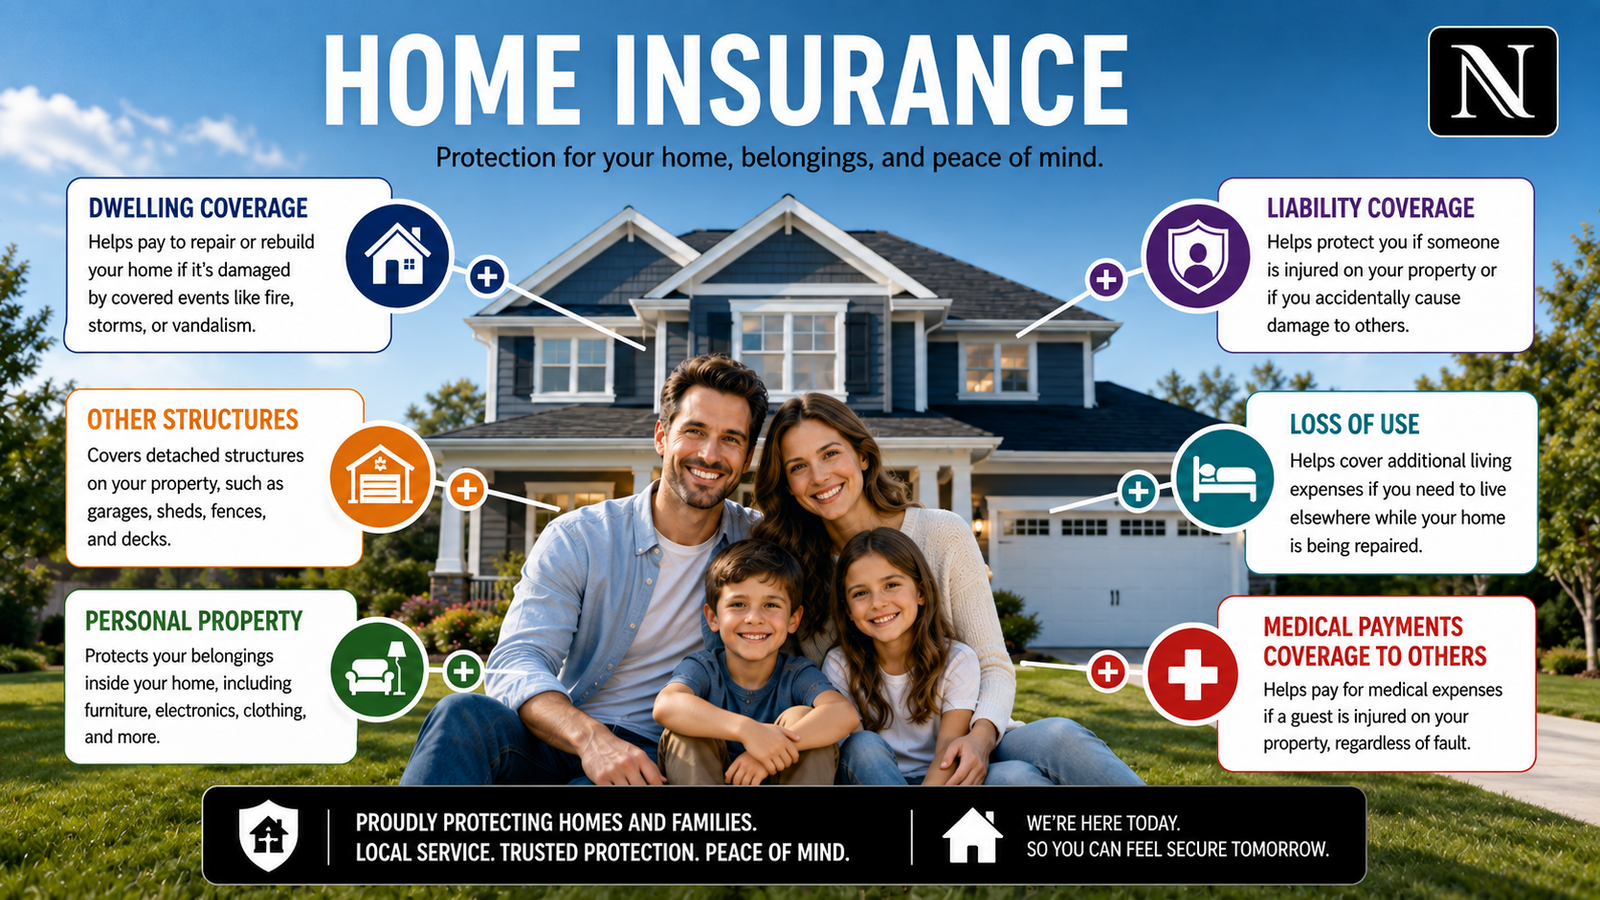
Standard homeowners insurance in Minnesota combines these building blocks. We’ll help you choose the ones that make sense for your home, your risk, and your budget.
Dwelling Coverage
Pays to repair or rebuild your home’s structure after a covered loss, such as fire, wind, hail, or lightning. Set it to your true rebuilding cost, not your home’s market value.
Personal Property Coverage
Covers your belongings — furniture, electronics, clothing — if they’re damaged, destroyed, or stolen, both inside your home and, to a lesser extent, away from it.
Personal Liability Coverage
Protects you financially if someone is injured on your property, or if you’re found responsible for damage to someone else’s property.
Loss of Use Coverage
Pays for temporary living expenses — like a hotel or short-term rental — if your home becomes uninhabitable after a covered loss.
Sewer & Water Backup Coverage
An optional but widely recommended add-on in Minnesota, since standard policies typically exclude damage from sewer or sump pump backups.
Ordinance or Law Coverage
Covers the added cost of rebuilding to current building codes, which is especially relevant for older Prior Lake and Scott County homes.
Why You Should Choose Us for Homeowners Insurance in Minnesota
We’re not tied to a single carrier. We compare rates and coverage across multiple Minnesota-licensed insurers to find the best fit for your home.
- We will shop for you — one conversation, multiple quotes. No need to repeat your information to five different call centers.
- We know Minnesota’s weather — hail, wind, and freeze/burst pipe claims all factor into how we recommend coverage.
- We’re local — based in Prior Lake, serving Scott County homeowners who deal with the same storms and seasons we do.
- We help with hard-to-place homes — including guidance on the Minnesota FAIR Plan for properties that don’t fit standard underwriting.
Common Ways to Save on Homeowners Insurance in Minnesota
Ask about these when you call — most homeowners qualify for at least two or three.
- Multi-policy bundling — combine home with auto insurance for one of the biggest available discounts.
- Monitored security & fire alarm systems — discounts for professionally monitored systems.
- Newer or updated roof — impact-resistant roofing can qualify for a meaningful rate reduction.
- Claims-free history — a clean record is rewarded across most carriers.
Proudly Serving Prior Lake, Savage, Scott County, and the Entire State of Minnesota
Prior Lake · Savage · Shakopee · Lakeville · Elko New Market · Credit River · Scott County, MN
Get a Real Quote on Homeowners Insurance in Minnesota from a Real Local Agent
No spam, no runaround — just a straightforward conversation about what coverage makes sense for your home and your budget.
Call 952-469-0412 or request a quote online.
Nelson Insurance Services · 952-469-0412 · Prior Lake, MN
Independent insurance agency serving Prior Lake, Savage, Shakopee, Lakeville, Scott County, and all of Minnesota. Auto, home, boat, and business insurance coverage from multiple carriers, chosen to fit you.
FAQ
No, Minnesota doesn’t have a state law requiring homeowners’ insurance. However, if you have a mortgage, your lender will require it for the life of the loan. Even without a mortgage, most homeowners carry coverage to protect against fire, storm damage, or a liability claim.
A standard policy typically covers your home’s structure (dwelling), personal belongings, personal liability, and temporary living expenses if a covered loss like fire, wind, hail, or lightning makes your home uninhabitable. Flood damage and sewer/water backup are usually excluded and require separate coverage.
Rates have climbed largely due to Minnesota’s frequent hail and wind events, rising construction and labor costs to rebuild homes, and higher reinsurance costs passed down to insurers — Minnesota saw one of the steepest rate increases in the nation in 2025. Shopping your policy across multiple carriers, rather than automatically renewing, is one of the most effective ways homeowners manage these increases.
The Minnesota FAIR Plan is the state’s insurer of last resort for homes that don’t qualify for standard coverage due to age, condition, location, or claims history. It’s not always the cheapest option, so it’s worth having an independent agent check standard-market carriers first before assuming the FAIR Plan is your only path to coverage.
GET A QUICK QUOTE
it only takes a minute
Ready to Protect What Matters Most?
Let's find the right coverage for you or your business.