Liquor Liability Insurance in Minnesota
Liquor Liability Insurance in Minnesota for Bars, Restaurants, and Breweries
Nelson Insurance Services is an independent local agency in Prior Lake, MN. We help bars, restaurants, breweries, and event venues across Minnesota meet Minnesota’s dram shop insurance requirements, keep their liquor license in good standing, and carry real protection beyond the statutory minimum.
Call 952-469-0412 for a Free Quote on Liquor Liability Insurance in Minnesota
What Minnesota Actually Requires from Liquor Licensees
Under Minnesota Statute § 340A.409, Minnesota cannot issue, maintain, or renew a retail liquor license without proof of liquor liability insurance. This is one of the few insurance types Minnesota mandates by statute, not by contract. The state’s minimum limits are specific: $50,000 for bodily injury to one person, $100,000 for bodily injury to two or more persons, $10,000 for property damage, and matching $50,000/$100,000 limits for loss of means of support, with a statutory aggregate minimum of $310,000 per policy year.
Local municipalities can — and often do — require higher limits than the state minimum before issuing a license. Minneapolis, for example, spells out these same statutory figures in its licensing requirements, so confirm your city or county’s threshold before assuming the state floor is enough.
Just as important: standard general liability policies exclude alcohol-related claims entirely for any business that sells or serves liquor. A separate liquor liability insurance policy in Minnesota, or an endorsement, isn’t an optional add-on — it’s the only coverage that responds to a dram shop claim. Get a quote for liquor liability insurance in Minnesota, or see how it pairs with general business insurance.
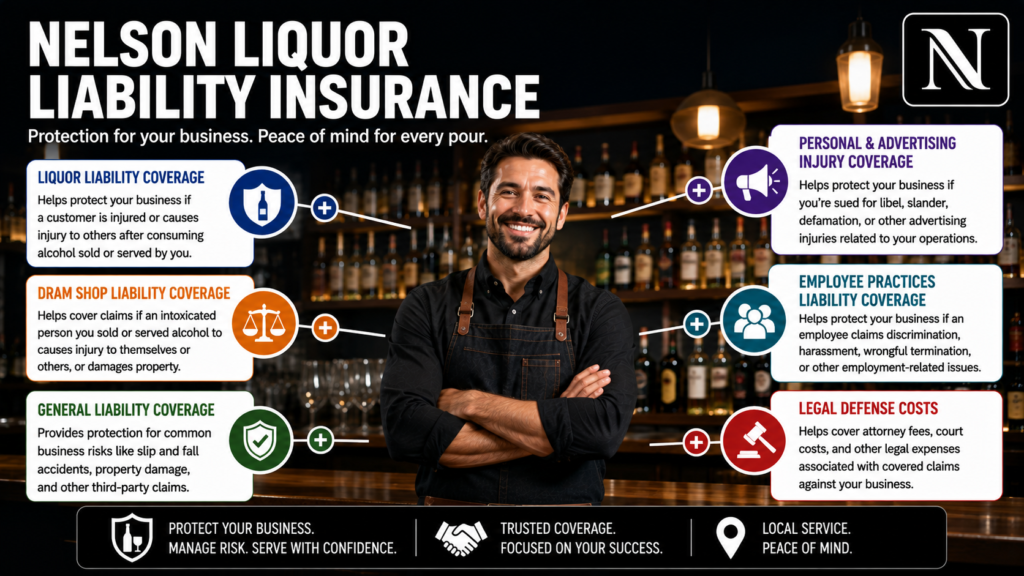
The Nelson Coverage Pour — From Statutory Minimum to Last Call
Liquor liability insurance in Minnesota often starts at the minimum, but it rarely should. Here’s how the three common levels compare for Minnesota establishments.
First Pour — Statutory Minimum
$50,000/$100,000 bodily injury limits with a $310,000 aggregate — enough to keep your license active, but far below what most serious dram shop claims cost. Most liquor liability attorneys consider this floor insufficient for real protection.
Full Bar — Standard Coverage
$1,000,000 per occurrence is the practical floor most carriers and license attorneys recommend. This is the most common setup for Prior Lake area bars, restaurants, and taprooms that want coverage matched to real-world claim sizes, not just the legal minimum.
Last Call — Complete Protection
Higher per-occurrence and aggregate limits for high-volume, late-night, or higher-risk operations, often paired with general liability and property coverage in a bundled commercial policy. Built for establishments that pour a lot of drinks and want a real safety margin.
What Liquor Liability Insurance Actually Covers
Minnesota’s Dram Shop Act creates a specific type of exposure, and liquor liability insurance in Minnesota is built to respond directly.
Third-Party Bodily Injury Claims
Covers injuries caused by a patron you served, including drunk driving accidents that happen after they leave your establishment — the most common and highest-cost type of dram shop claim.
Property Damage Claims
Covers property damage caused by an intoxicated patron you served, whether it happens on your premises or elsewhere.
Loss of Means of Support Claims
A uniquely dram-shop-specific coverage, addressing claims from dependents who lose financial support due to an incident tied to your alcohol service.
Legal Defense Costs
Covers attorney fees and legal defense costs for a dram shop claim, which can be substantial even before any settlement or judgment.
What It Doesn’t Cover
Liquor liability policies generally exclude intentional acts and criminal penalties, and they don’t cover your business’s property damage or your own injuries—those require separate commercial property and general liability coverage.
Which Businesses Need Liquor Liability Insurance in Minnesota?
Any business licensed to manufacture, distribute, sell, or serve alcohol in Minnesota needs liquor liability insurance in Minnesota — it isn’t optional, and it isn’t included in a standard policy.
- Bars, taverns, and nightclubs — the classic dram shop exposure, especially for late-night operations.
- Restaurants with a liquor license — full-service dining with bar service carry the same statutory requirement as a standalone bar.
- Breweries, taprooms, and wineries — production facilities with on-site tasting rooms are licensed vendors under Minnesota law.
- Event venues, caterers, and golf courses with a bar — anywhere alcohol is served to the public or event guests.
- One-time special event permit holders — a temporary permit still creates dram shop exposure for the event.
Not sure how your establishment is classified? Contact us, and we’ll walk through your specific license requirements.
Why Businesses Choose Us for Your Liquor Liability Insurance in Minnesota.
We’re not tied to a single carrier. We compare rates and coverage across multiple Minnesota-licensed insurers to build a policy that satisfies your license and protects your business.
- We shop it for you — one conversation, multiple quotes, no repeating your information to five different call centers.
- We know what your license requires — including local municipal minimums that can exceed the state’s statutory floor.
- We’re local — based in Prior Lake, serving Scott County bars, restaurants, and breweries along the lake and around town. But we do write coverage statewide.
- We handle the cancellation notice requirement — since Minnesota law requires your insurer to notify your licensing authority before a policy lapses, and we make sure that never catches you off guard.
Common Ways Minnesota Establishments Manage Liquor Liability Costs
Ask about these when you call — most establishments can meaningfully affect their rate.
- Responsible beverage service training — completing a recognized server training program (like TIPS) can reduce your premium.
- Bundling with general liability and property — combining coverage into one commercial policy often lowers the total cost.
- Claims-free history — a clean claims record is rewarded across most carriers.
- Documented ID-checking and cutoff policies — clear house policies on service can support a stronger rate over time.
Proudly Serving Establishments Across Prior Lake, Scott County and Greater Minnesota
Prior Lake · Savage · Shakopee · Lakeville · Elko New Market · Credit River · Scott County, MN
Get a Real Minnesota Liquor Liability Quote from a Real Local Agent
No spam, no runaround — just a straightforward conversation about what your license requires and what coverage actually protects your business.
Nelson Insurance Services · 952-469-0412 · Prior Lake, MN
Independent insurance agency serving Prior Lake, Savage, Shakopee, Lakeville, Scott County, and all of Minnesota. Get business insurance coverage from multiple carriers, chosen to fit you.
FAQ
Yes. Under Minnesota Statute 340A.409, you must provide proof of liquor liability insurance before the state can issue, maintain, or renew a retail liquor license. The state sets minimum limits, and local municipalities can require higher minimums before granting a license.
No. Standard general liability policies specifically exclude liquor liability for any business that sells or serves alcohol. A separate liquor liability policy or endorsement is required to cover dram shop claims — general liability alone will not respond. See our general liability insurance page for how the two work together.
Minnesota’s Dram Shop Act defines an illegal sale as serving an obviously intoxicated person (shown through signs like slurred speech or impaired coordination), serving a minor regardless of the ID presented, selling during prohibited hours, or selling without a proper license. A dram shop claim doesn’t require proof your server knew someone was impaired — only that the signs were observable.
Generally, yes. A temporary or special event liquor permit still creates dram shop exposure for that event, and most municipalities require proof of liquor liability coverage as part of the special event permit process, even if the coverage only needs to last for the day of the event.
GET A QUICK QUOTE
it only takes a minute
Ready to Protect What Matters Most?
Let's find the right coverage for you or your business.